

Three steps to better investment decisions: know the rules, read behaviour, know yourself
No asset class suits everyone. Before investing, investors need to understand how an asset creates value, observe market behaviour, and be clear about their own goals, risk tolerance and financial position.
No asset class suits everyone. Before investing, investors need to understand how an asset creates value, observe market behaviour, and be clear about their own goals, risk tolerance and financial position.
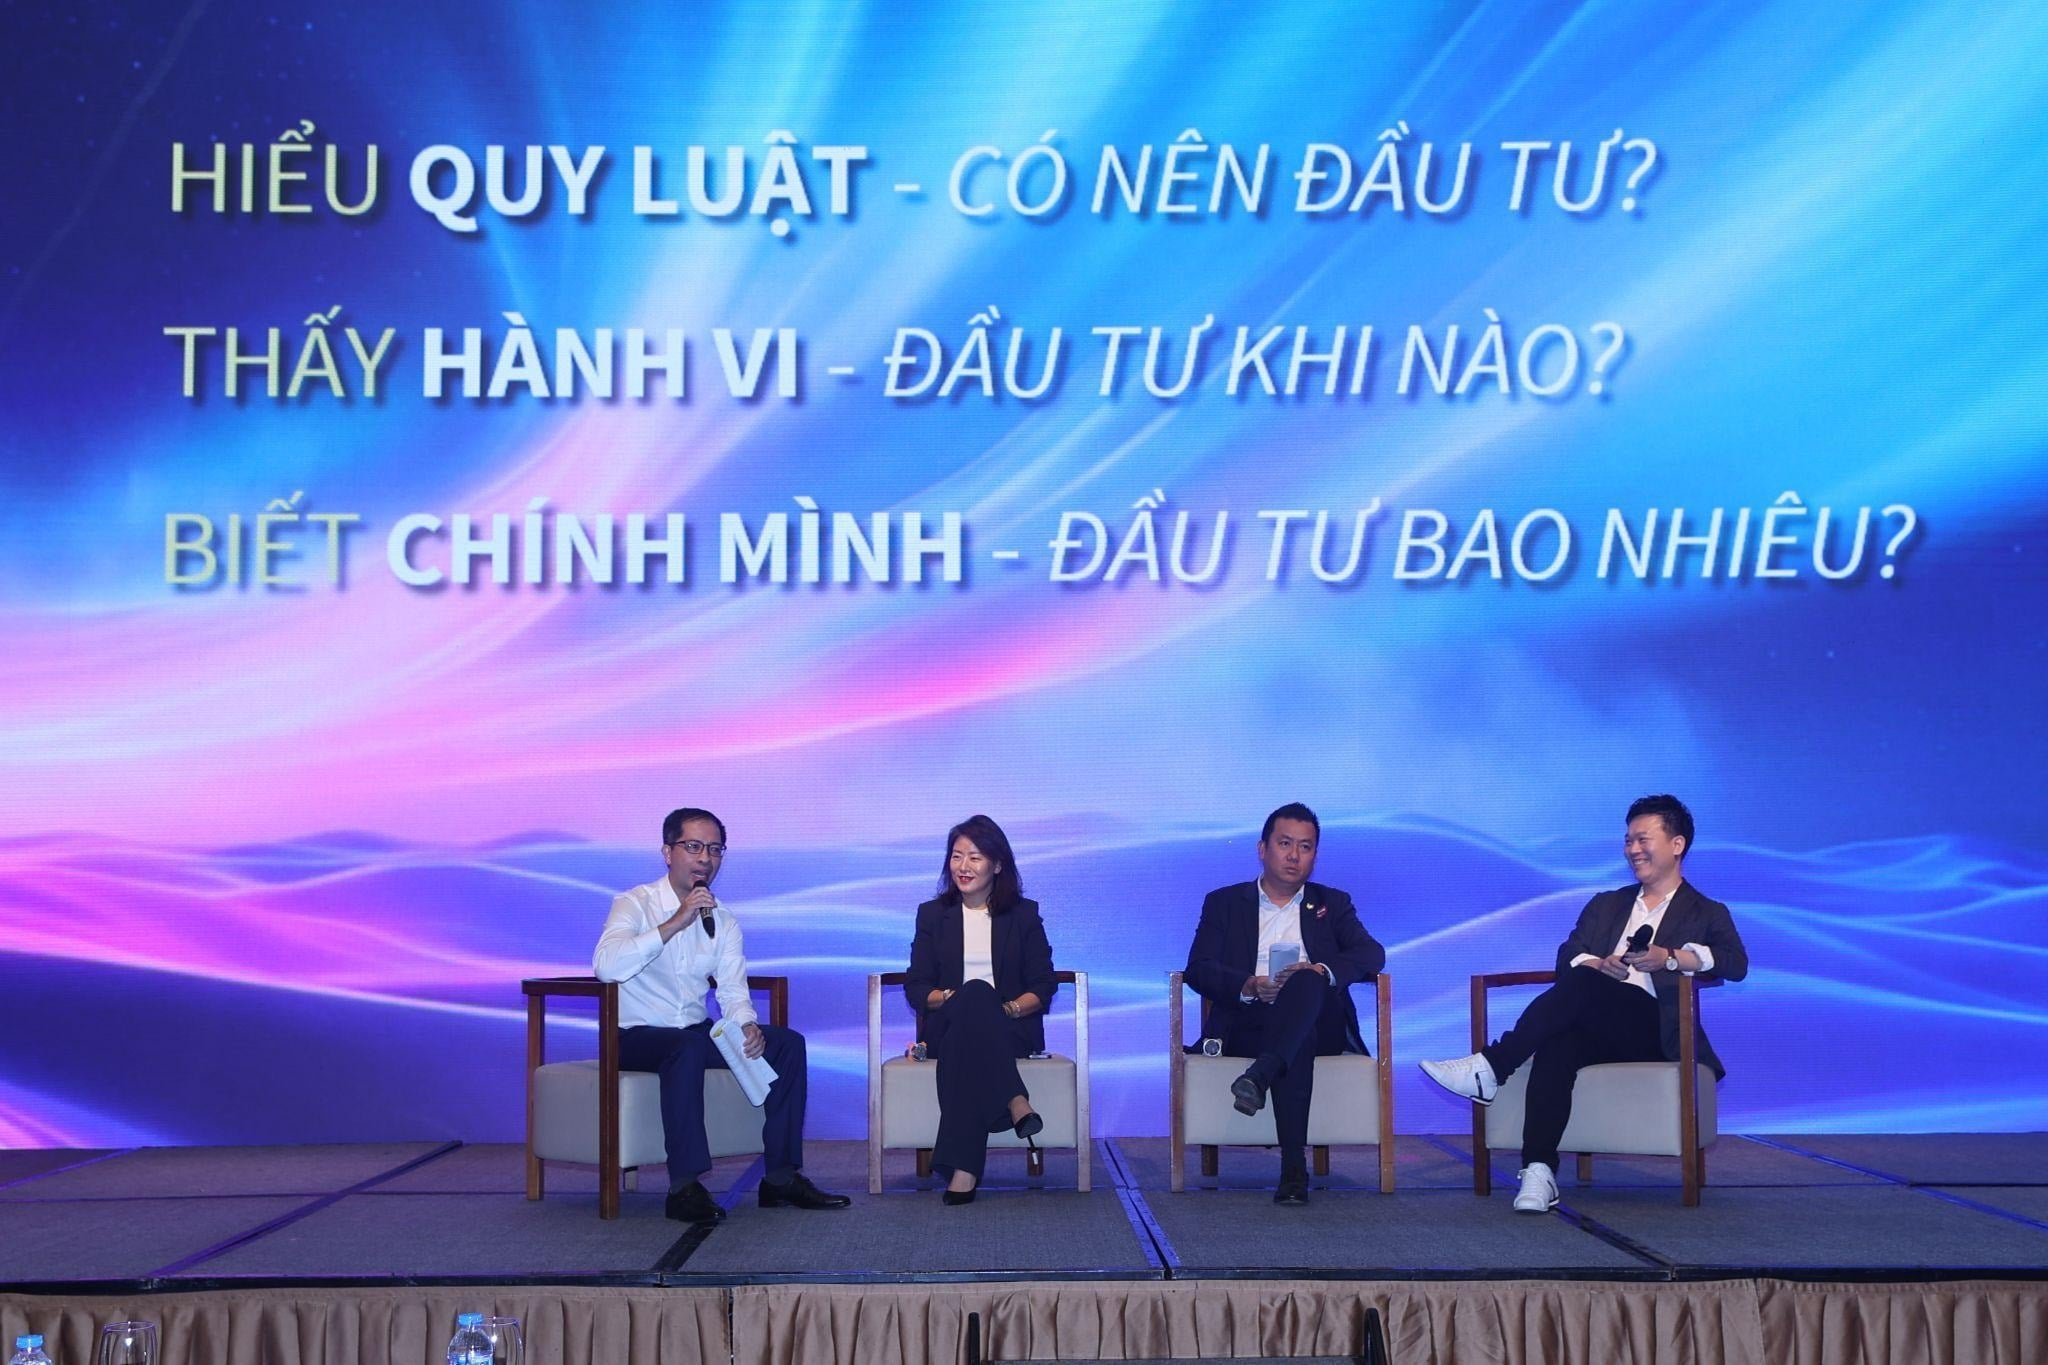
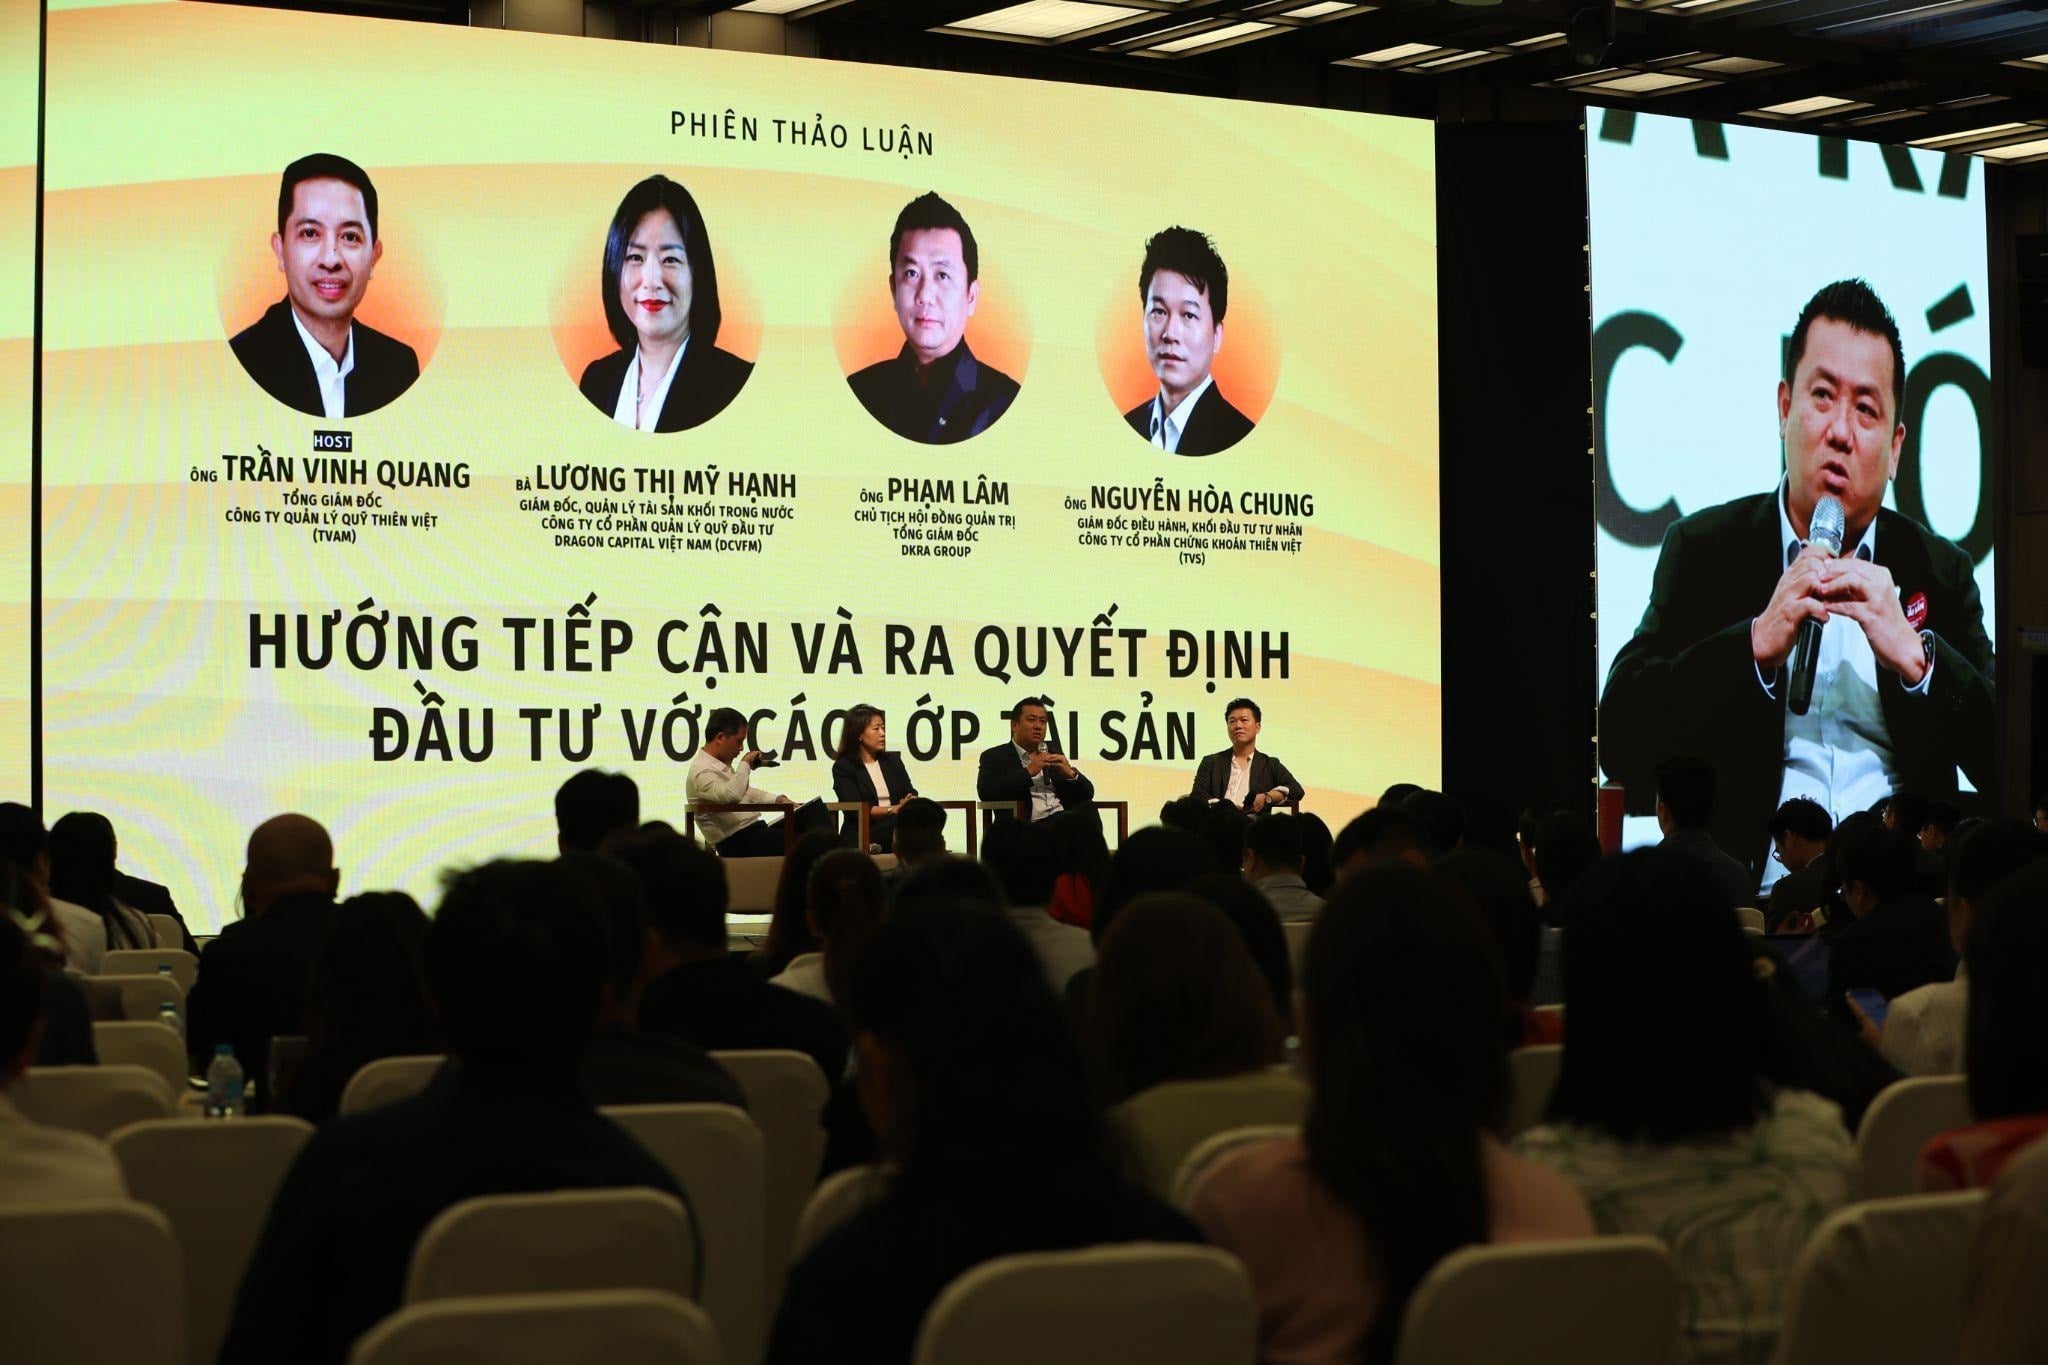
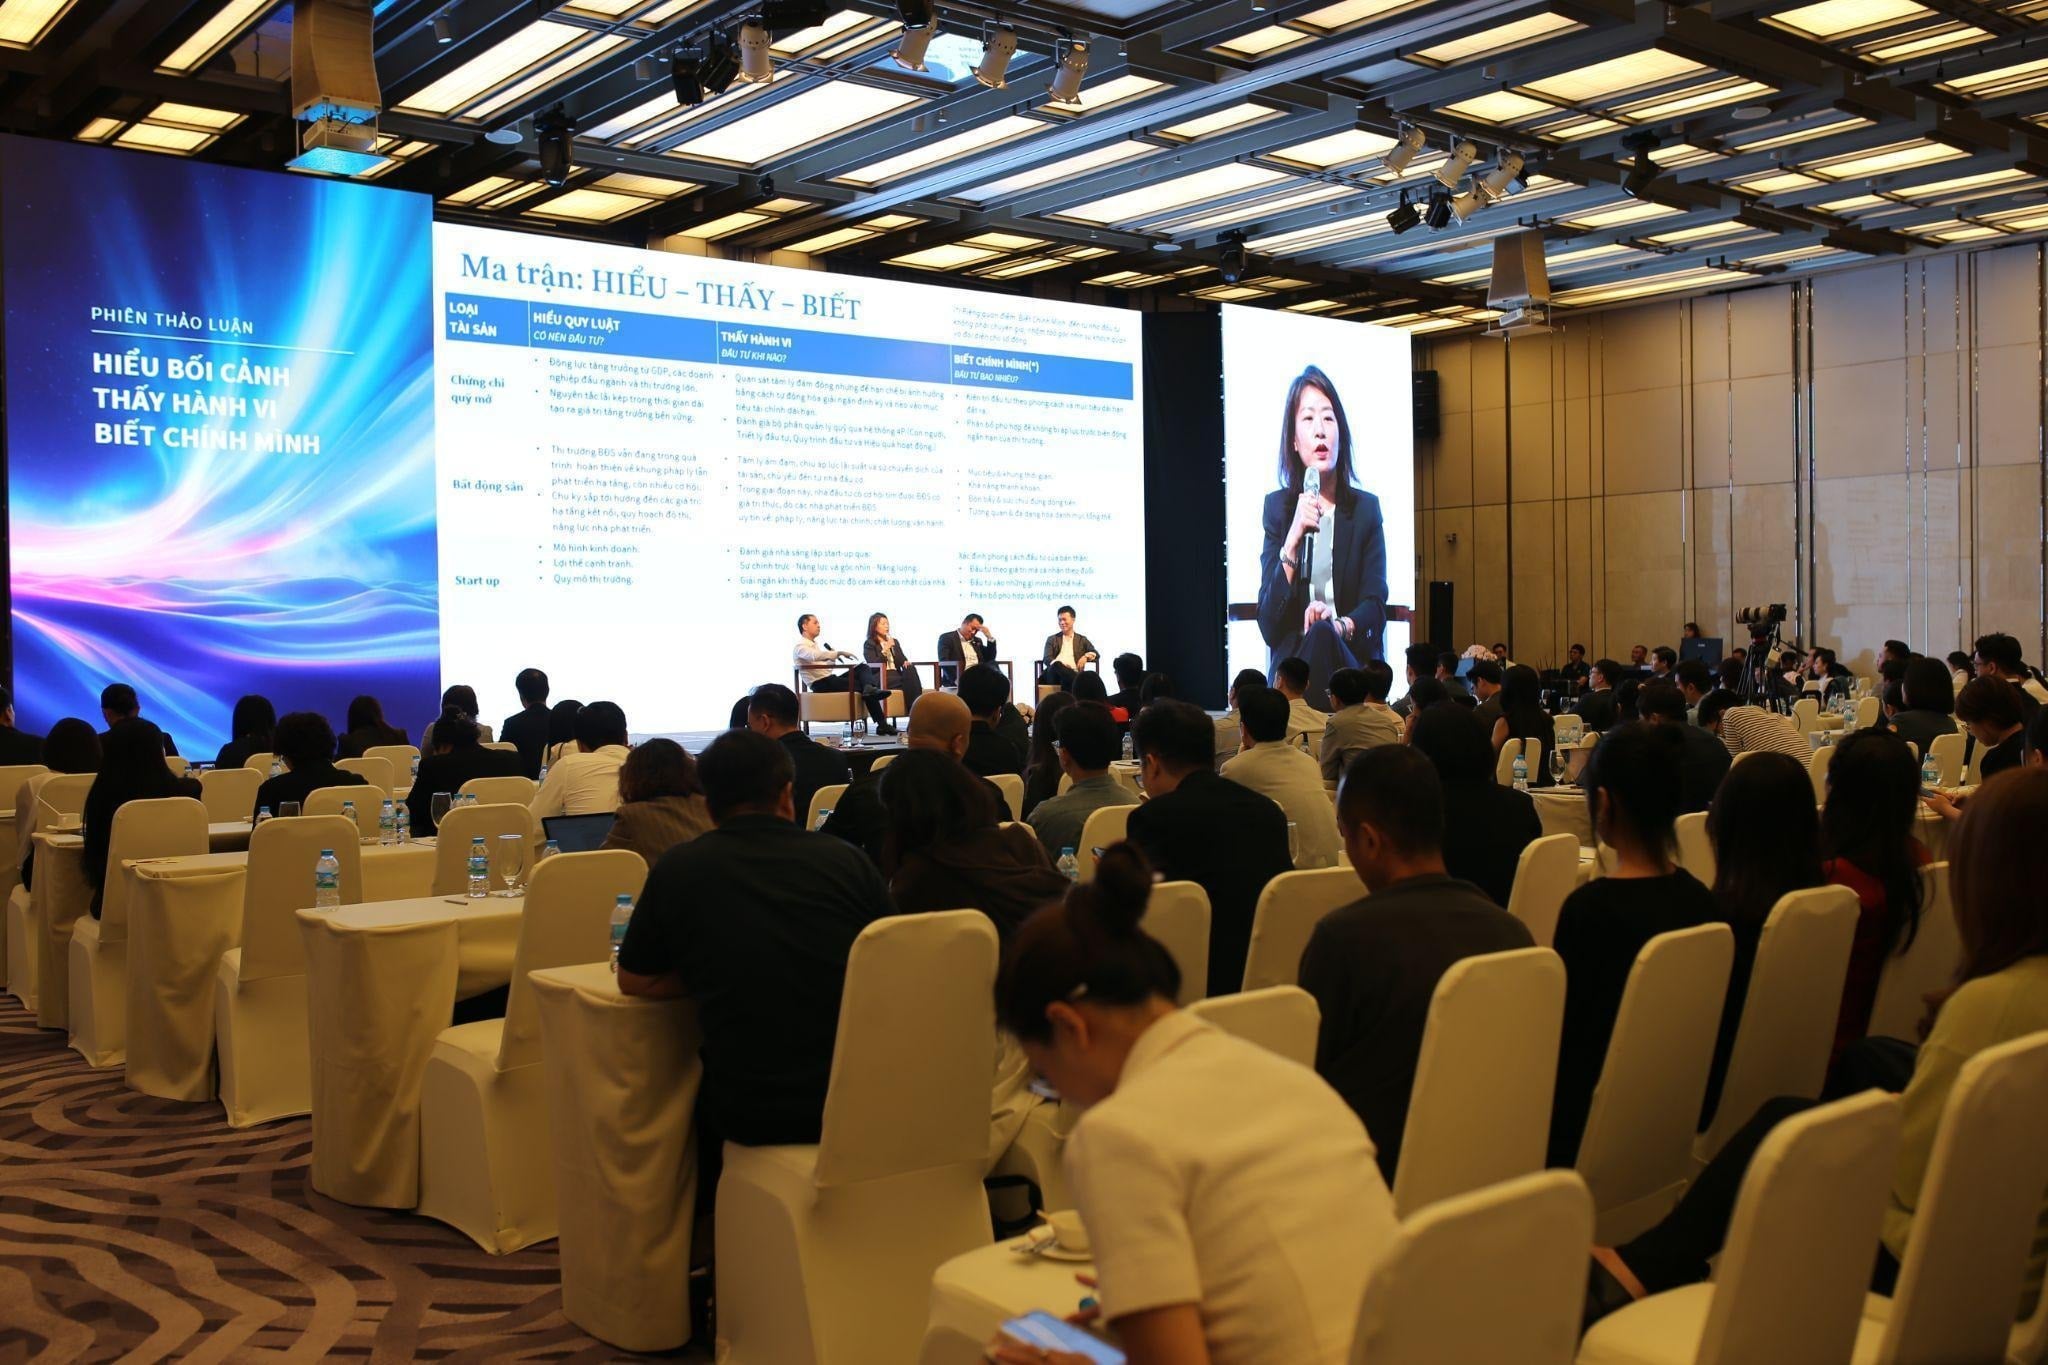
At the panel "Approaching and deciding on investments across asset classes" at Investment Conference 2026: New Flows of Assets, Tran Vinh Quang, chief executive of Thien Viet Asset Management (TVAM), discussed the topic with Luong Thi My Hanh, director of domestic asset management at Dragon Capital Vietnam; Pham Lam, chairman and chief executive of DKRA Group; and Nguyen Hoa Chung, managing director of private investment at Thien Viet Securities (TVS).
Know the rules: where does value come from?
According to Tran Vinh Quang, investors should not start by asking which asset is "hot", but by understanding where the value of each asset class comes from.
With fund certificates, for instance, Luong Thi My Hanh said growth is rooted in the economy, with leading listed companies typically growing at least twice as fast as GDP. Open-ended funds let investors participate through a professionally managed, diversified portfolio and benefit from compounding.
The value creation rules for real estate, by contrast, have changed over the past three to five years. Pham Lam said buying land in remote areas and waiting for subdivision or rapid price appreciation is no longer easy. Investors need to assess infrastructure, zoning, location and usability, with cash flow a critical criterion. In an illiquid market, even a 20% to 30% or 30% to 40% drop in asset value is no guarantee of a sale. Real estate therefore requires a medium- to long-term view.
From the startup perspective, Nguyen Hoa Chung pointed to three factors: the business model, competitive advantage and market size. Investors need to understand how a company makes money, its revenue and cost efficiency and its ability to scale, while the founding team must demonstrate a strategy for building an advantage.
Read behaviour: watch the people behind the asset
Understanding how an asset works is only the first step. A good opportunity can still become a poor investment if the investor lacks discipline or picks the wrong people to back.
With startups, Chung said, investors should examine the founder's integrity, capability, market knowledge, resilience and level of commitment. Commitment shows up in time, resources and the opportunities the founder has turned down.
On the stock market, the first subject to observe is the investor themselves. Hanh said loss aversion and overreaction to short-term volatility lead many people to buy when the market rises and withdraw when prices fall.
Drawing on 22 years of data from the DCDS fund (the DC Dynamic Securities Investment Fund managed by Dragon Capital), Hanh said a "prophetic investor" who always bought at the monthly low would accumulate only about 2.7% more than someone investing a fixed amount every month. Rather than timing the market, investors should tie their investments to goals, maintain discipline and let compounding work.
On real estate, Lam noted that strategic investors still look for cash-flow-generating assets while assessing a developer's experience, finances, brand and execution quality.
Know yourself: there is no best asset
After understanding the rules and observing behaviour, the final step brings the focus back to the investor. Quang said experts can analyse opportunities but cannot decide for anyone how much to allocate to equities, real estate or startups. The answer depends on goals, life circumstances, financial position and risk tolerance.
The three panellists illustrated this with different approaches to fields outside their own expertise. Lam chooses areas he is passionate about and puts his trust in the people leading the project, even when maximising returns is not the only priority.
Hanh has moved from impulsive asset purchases to an approach based on objectives, holding period, liquidity needs and the role an asset plays in the portfolio. "There is no best asset, only a suitable one," she stressed.
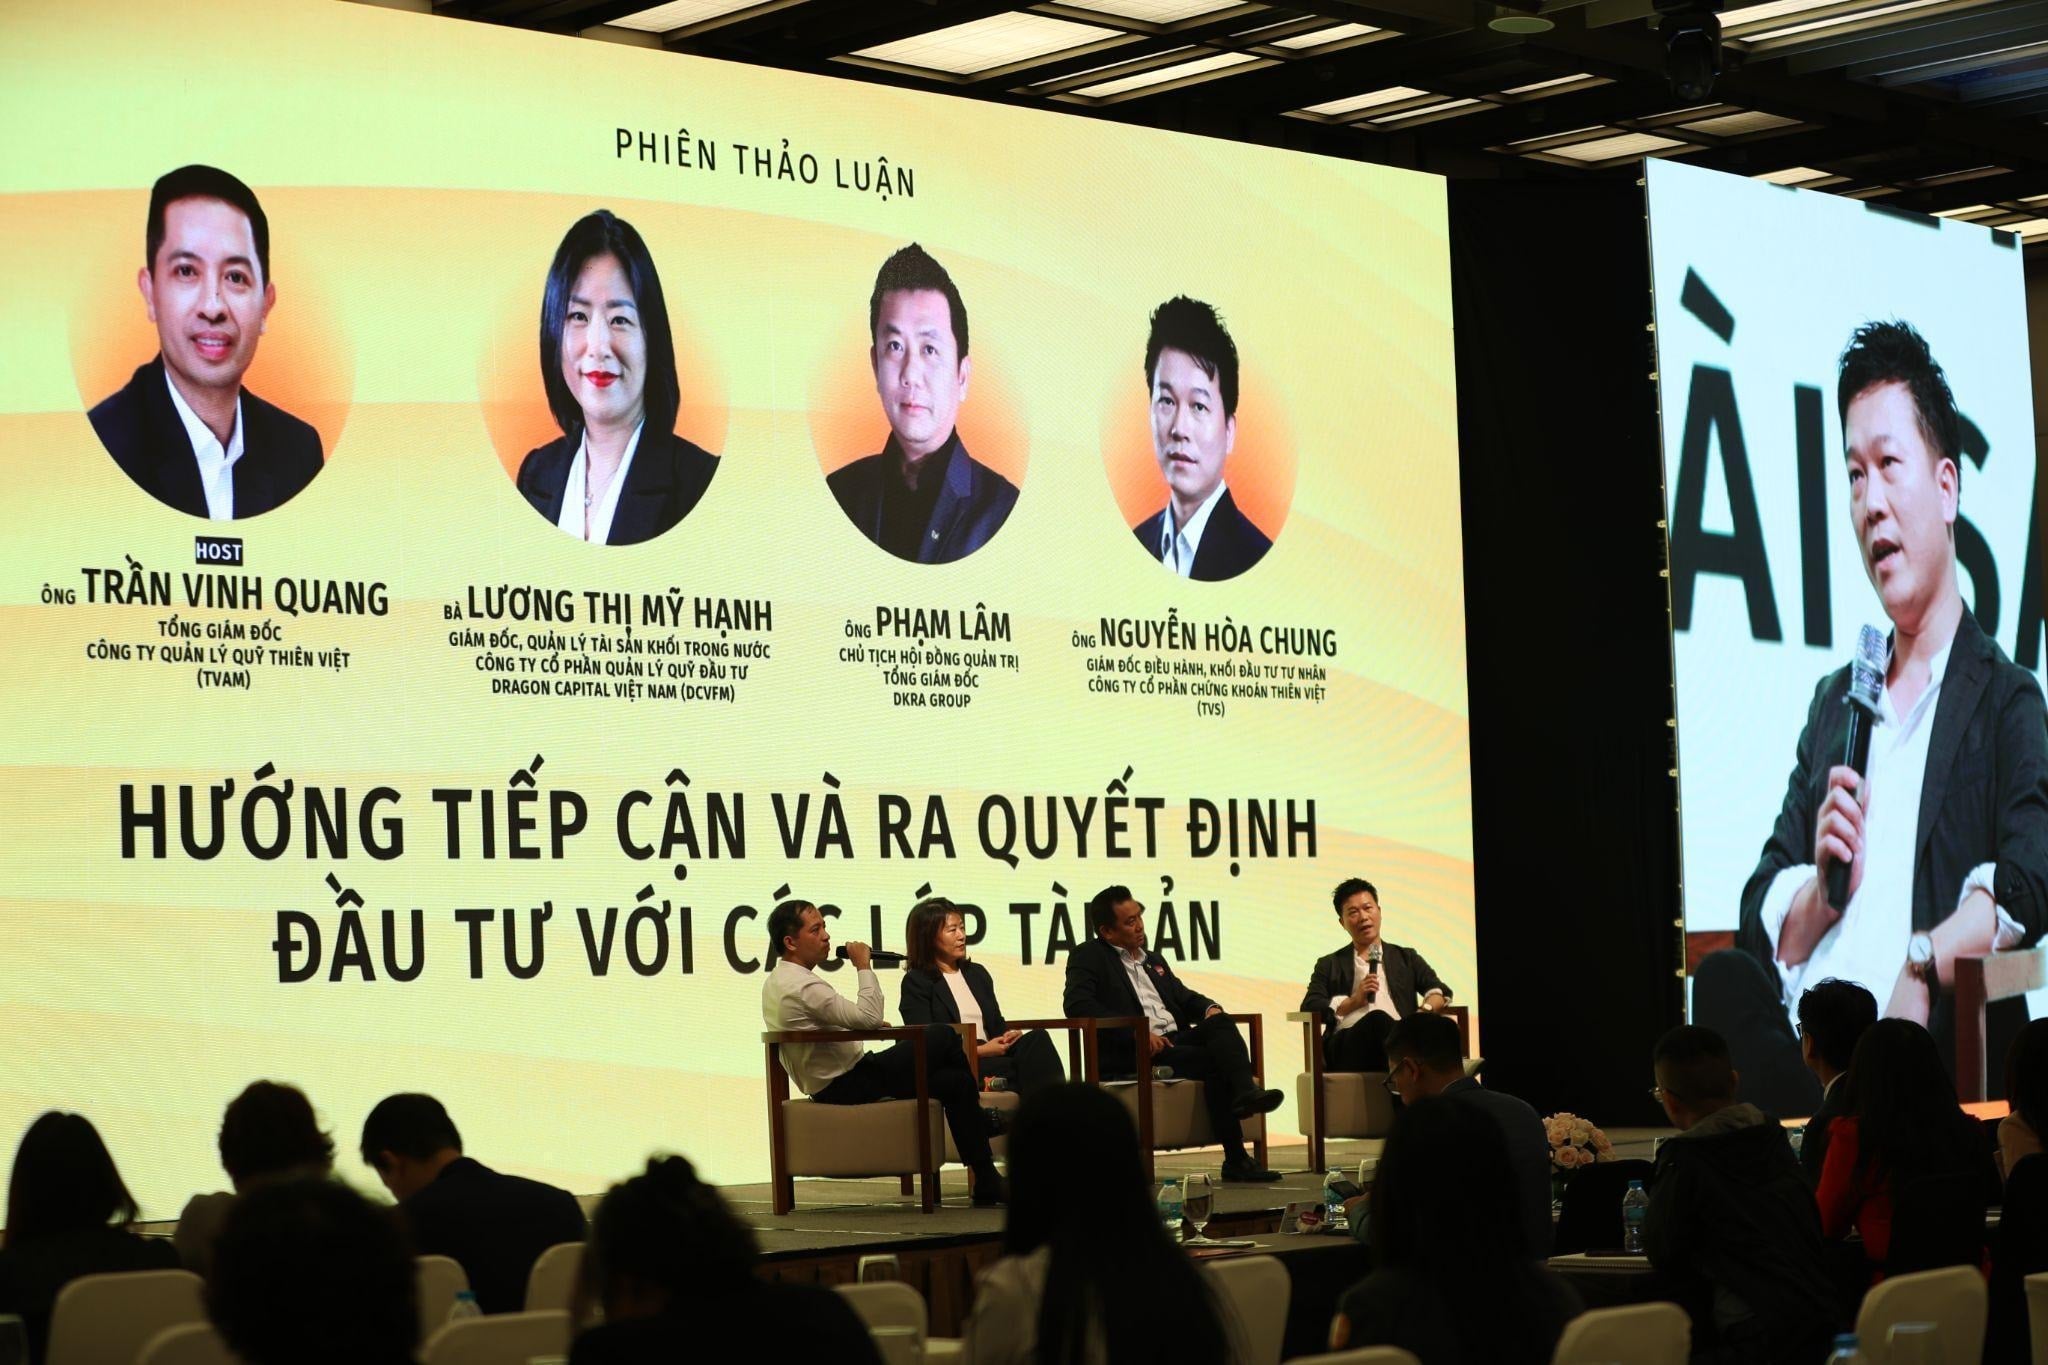
Chung argued that everyone must honestly determine whether they are an investor or a speculator. A common mistake is buying with short-term expectations and then, when the call proves wrong, convincing oneself to hold for the long term; or declaring a long-term horizon and then selling out when prices swing. Because he pursues long-term investing, he does not use leverage, since debt can force asset sales at the worst possible moment.
The three perspectives converge on one principle: a good opportunity does not mean everyone should allocate the same proportion to it. Age, family responsibilities, cash flow and risk tolerance determine how much each person can invest.
In closing, Quang's test is whether an investment lets you "sleep well". If a decision leaves an investor uneasy, the allocation may have exceeded their risk tolerance.
Source: TheLeader — theleader.vn. Republished to share knowledge with founders and investors in the HCM VIF ecosystem.
Category & tags
Related news
 Ecosystem
Venture capital will be a new asset class
Mr. Hoang Duc Trung believes that, with the State taking the lead and large organizations and enterprises joining forces to spread the momentum, venture capital will fulfil its role as an engine of growth and innovation
 Finance & Banking05/2026
The success of a public-private venture fund is not measured by the number of unicorns
With an initial size of VND 500 billion, how will the government's “seed capital” from the public-private venture fund catalyze the flow of financing into startups?
 Finance & Banking18/05/2026
Ho Chi Minh City sets up venture capital fund: 'Seed capital' for Vietnamese tech
For the first time, Ho Chi Minh City has a venture capital fund operating under a joint-stock company model with the participation of the State and major private corporations.