

The 'credit room' is unchanged, but capital flows have shifted direction
The credit story of 2026 lies not only in the issue of the "room" but in how capital is allocated toward priorities efficiently and creates long-term value for the economy.
The credit story of 2026 lies not only in the issue of the "room" but in how capital is allocated toward priorities efficiently and creates long-term value for the economy.
After the first half of 2026, the State Bank of Vietnam (SBV) still maintains a cautious credit growth orientation of around 15–16%, significantly lower than the 19% increase of the previous year. Pressure to expand capital flows is mounting as the economy needs greater resources to realize its double-digit growth target.
An SBV representative once noted that on average, more than 2% of credit growth can support about 1% of GDP growth. This poses a challenge, as the credit needed to support a high growth target may require a level of 18–20%.
However, instead of sharply adjusting the credit quota for the entire system, the regulator is choosing a different approach: expanding capital headroom by removing limits within the operating mechanism.
These include measures to loosen liquidity, capital-use ratios, and the way quotas are calculated for certain priority sectors.
This reflects a new approach to policy management. Whereas in previous years the story revolved around "loosening the credit room," this year new tools have been applied, with the goal of channeling capital to the right places, contributing maximally to the economy's growth needs.
A more flexible credit mechanism
The SBV's first step focuses on improving the banking system's capacity to supply capital.
In May 2026, the SBV issued Circular 08/2026/TT-NHNN, allowing 20% of the State Treasury's term deposits to be counted in the funding used to calculate the loan-to-deposit ratio (LDR), thereby expanding the ability to supply credit.
At the same time, the SBV allowed 25 commercial banks not to count the additional outstanding loans for social housing, industrial parks, and export processing zones in their real estate credit balance in 2026.
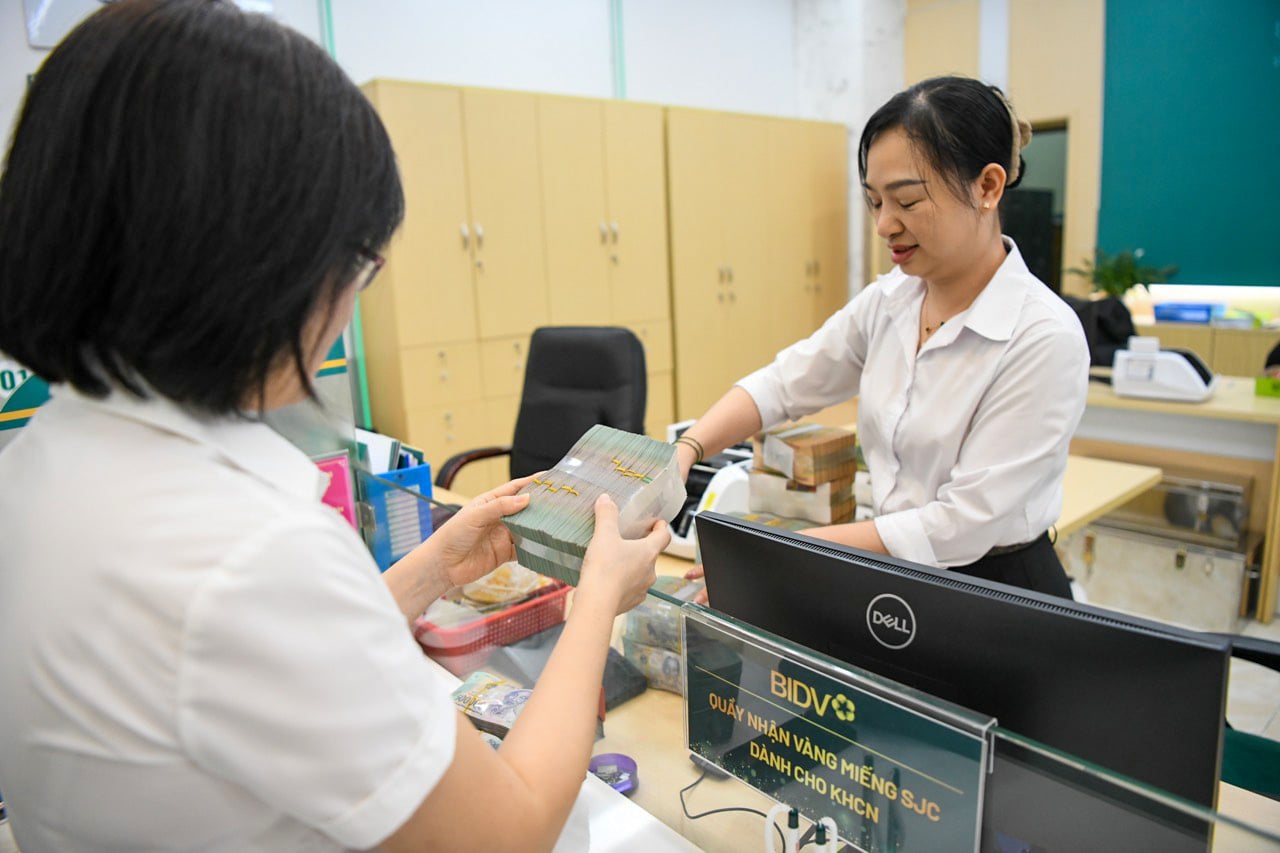
Adjusting the limit ratios gives banks more room to balance their capital sources. Photo: HA
On June 22, Circular 25 brought another important change by raising the ceiling on the ratio of short-term funds used for medium- and long-term lending from 30% to 40%. At the same time, the new regulation added a special case allowing part of the State Treasury's term deposits to be counted in the LDR formula at a level higher than the normal maximum.
Most recently, the SBV continued to issue Official Letter 4551/NHNN-CSTT to "unlock" the credit room for industrial-park real estate and social housing; it also issued Official Letter 5386/NHNN-TD allowing commercial banks to exclude the outstanding loans extended to 18 key projects with a capital need of about VND752 trillion belonging to Vingroup, Sun Group, and Masterise from the credit growth quota.
These adjustments are expected to create additional large headroom for medium- and long-term credit, especially for sectors that need long-term capital such as infrastructure, construction, manufacturing, industrial-park real estate, and capacity-expansion projects.
As such, although the nominal credit room remains at around 15%, the scope of application and the method of calculation have changed. In practice, the amount of capital that can be injected into the economy is likely to be larger than the figure initially announced.
Capital flows to where growth is created
The most notable point in the series of new policies lies in how the SBV chooses where to expand credit space.
The regulator is not simply promoting credit growth evenly across regions and target groups, but is creating more favorable conditions for sectors, projects, and the "locomotives" that lead and that can convert capital efficiently in investment, construction, and the expansion of economic capacity.
First of all, the banking system remains the most important "bloodstream" in this process. As the economy enters a phase requiring larger amounts of capital, the ability to supply capital depends heavily on liquidity headroom and the funding structure of credit institutions.
Adjusting limits such as the ratio of short-term funds for medium- and long-term lending, or the way LDR is calculated, gives banks more room to balance their capital sources, especially amid rising demand for long-term loans for infrastructure, industrial, and expansion investment projects.
According to MB Securities (MBS), raising the ceiling on the ratio of short-term funds for medium- and long-term lending helps banks reduce liquidity pressure when expanding long-tenor lending, especially for large projects. At the same time, this change also helps reduce the pressure to mobilize long-term funds at high cost, thereby supporting control of funding costs and lending rate levels.
At the next layer, capital is being channeled toward areas capable of creating larger spillover effects.
The SBV's exclusion of outstanding loans for social housing, industrial parks, and export processing zones from the real estate credit control quota shows a clearer distinction between credit groups.
A loan serving the construction of social housing, the development of an industrial park, or the expansion of a factory is capable of creating a broader value chain, because it drives demand for construction, materials, labor, transport, and related services.
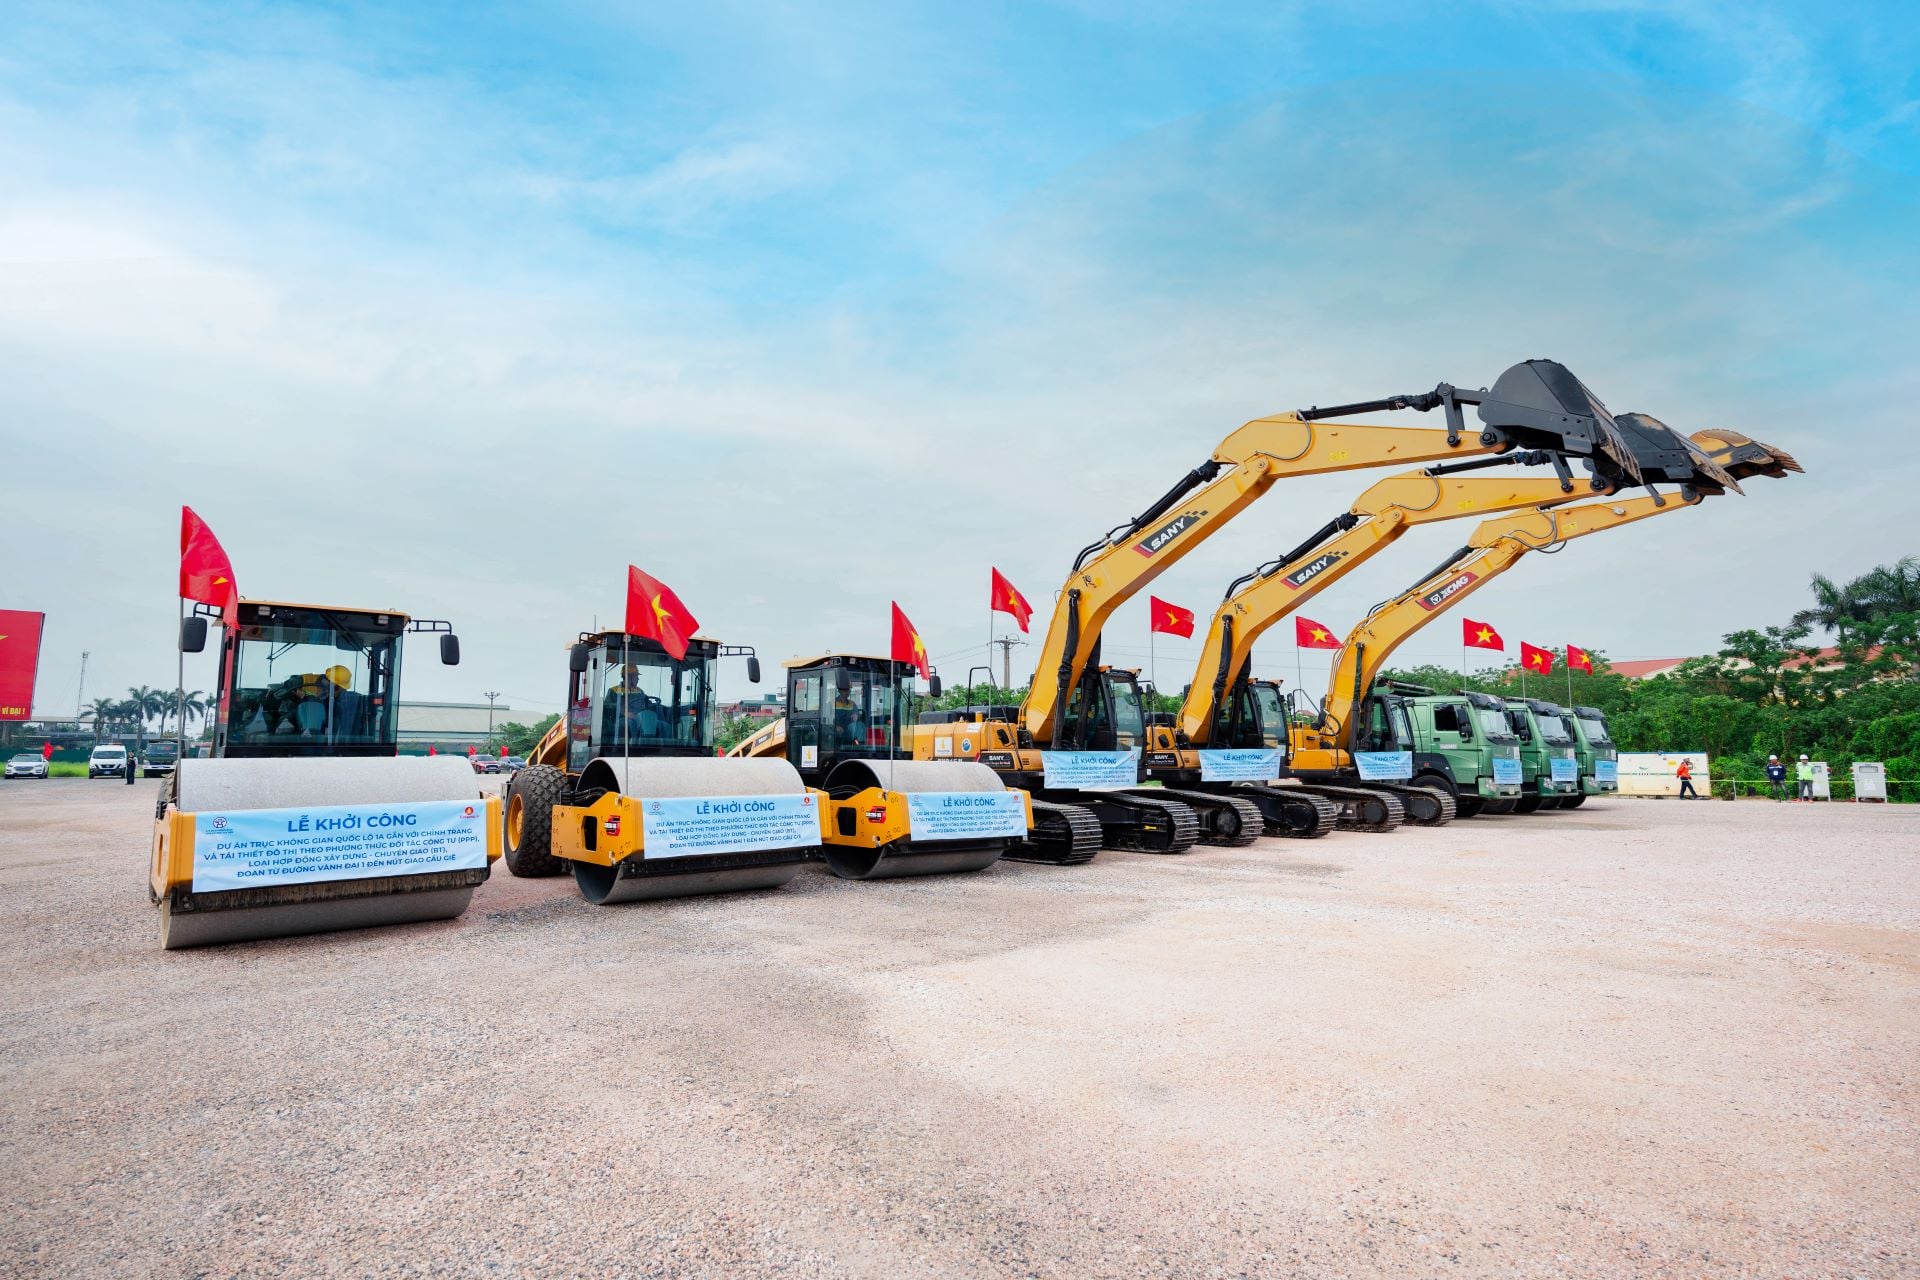
The city of Hanoi and Vingroup continue to study the expansion of the National Highway 1A spatial axis. Photo: Vingroup
Similarly, the exclusion of the outstanding loans of 18 key projects from the credit growth quota also reflects a new view of the role of large projects in the economy.
What matters is not only the size of the enterprise but also its ability to turn capital into new economic value. A project that can create additional construction, manufacturing, and infrastructure-expansion capacity, or drive many related industries, will have a different impact from capital that merely increases asset values in the short term.
According to Dr. Ho Quoc Tuan, Senior Lecturer at the University of Bristol, UK, the core issue lies not in the fact that a few enterprises benefit, but in the change in how capital flows are viewed. Accordingly, loans serving infrastructure, manufacturing, and priority sectors may be assessed differently within the credit allocation mechanism.
Controlling the quality of capital flows
The change in credit management is taking place as the SBV must balance multiple objectives at once: promoting growth, controlling inflation, and stabilizing the exchange rate.
In this environment, comprehensively loosening monetary policy is not an easy choice. Instead, credit management is shifting toward being more selective, focusing on the efficiency of capital use.
According to FiinRatings, the SBV's issuance of new policies reflects a shift in management priorities, from a phase focused on strengthening system safety to balancing that with the goal of supporting economic growth.
However, expanding credit headroom also places higher demands on the banking system. With more room for growth, credit institutions need to enhance their risk management capacity, optimize their loan portfolios, and prepare for higher governance standards in the future, such as Basel III.
Therefore, the story of 2026 lies not only in whether the credit room is expanded. The more important point is that the way capital is being allocated is changing.
Credit resources are being channeled toward areas capable of creating additional production capacity, driving investment, and playing a leading role in a new growth era.
Source: TheLeader — theleader.vn. This article is republished for the purpose of sharing knowledge with the community of founders and investors within the HCM VIF ecosystem.
Category & tags
Related news
 Ecosystem
Venture capital will be a new asset class
Mr. Hoang Duc Trung believes that, with the State taking the lead and large organizations and enterprises joining forces to spread the momentum, venture capital will fulfil its role as an engine of growth and innovation
 Finance & Banking05/2026
The success of a public-private venture fund is not measured by the number of unicorns
With an initial size of VND 500 billion, how will the government's “seed capital” from the public-private venture fund catalyze the flow of financing into startups?
 Finance & Banking18/05/2026
Ho Chi Minh City sets up venture capital fund: 'Seed capital' for Vietnamese tech
For the first time, Ho Chi Minh City has a venture capital fund operating under a joint-stock company model with the participation of the State and major private corporations.