

State Bank of Vietnam Affirms It Will Not Reverse Monetary Policy
The overarching goal of the regulator remains to keep lending rates at a reasonable level to support economic recovery and growth.
The overarching goal of the regulator remains to keep lending rates at a reasonable level to support economic recovery and growth.
Even as the State Bank of Vietnam has repeatedly asked credit institutions to keep interest rates stable and reduce funding costs to support businesses and drive economic growth, the market has still seen many commercial banks raise deposit rates at certain terms. This divergence has raised concerns about the flow of funds within the banking system.
At a recent regular press briefing, the SBV said the cause did not stem from a change in monetary-policy direction, but from a shift in the supply-demand balance of the system’s funds.
When credit growth outpaces deposit mobilization by a wide margin, liquidity pressure at some banks increases, forcing these units to adjust input interest rates to attract more funds to serve lending.
Credit continues to grow faster than deposits
As of June 26, 2026, outstanding credit across the system reached more than VND 19.97 quadrillion, up 7.41% from the end of 2025 and up 18.1% year-on-year. This is a fairly strong increase for just the first half of the year, reflecting the clearly recovering capital demand of businesses and the economy.
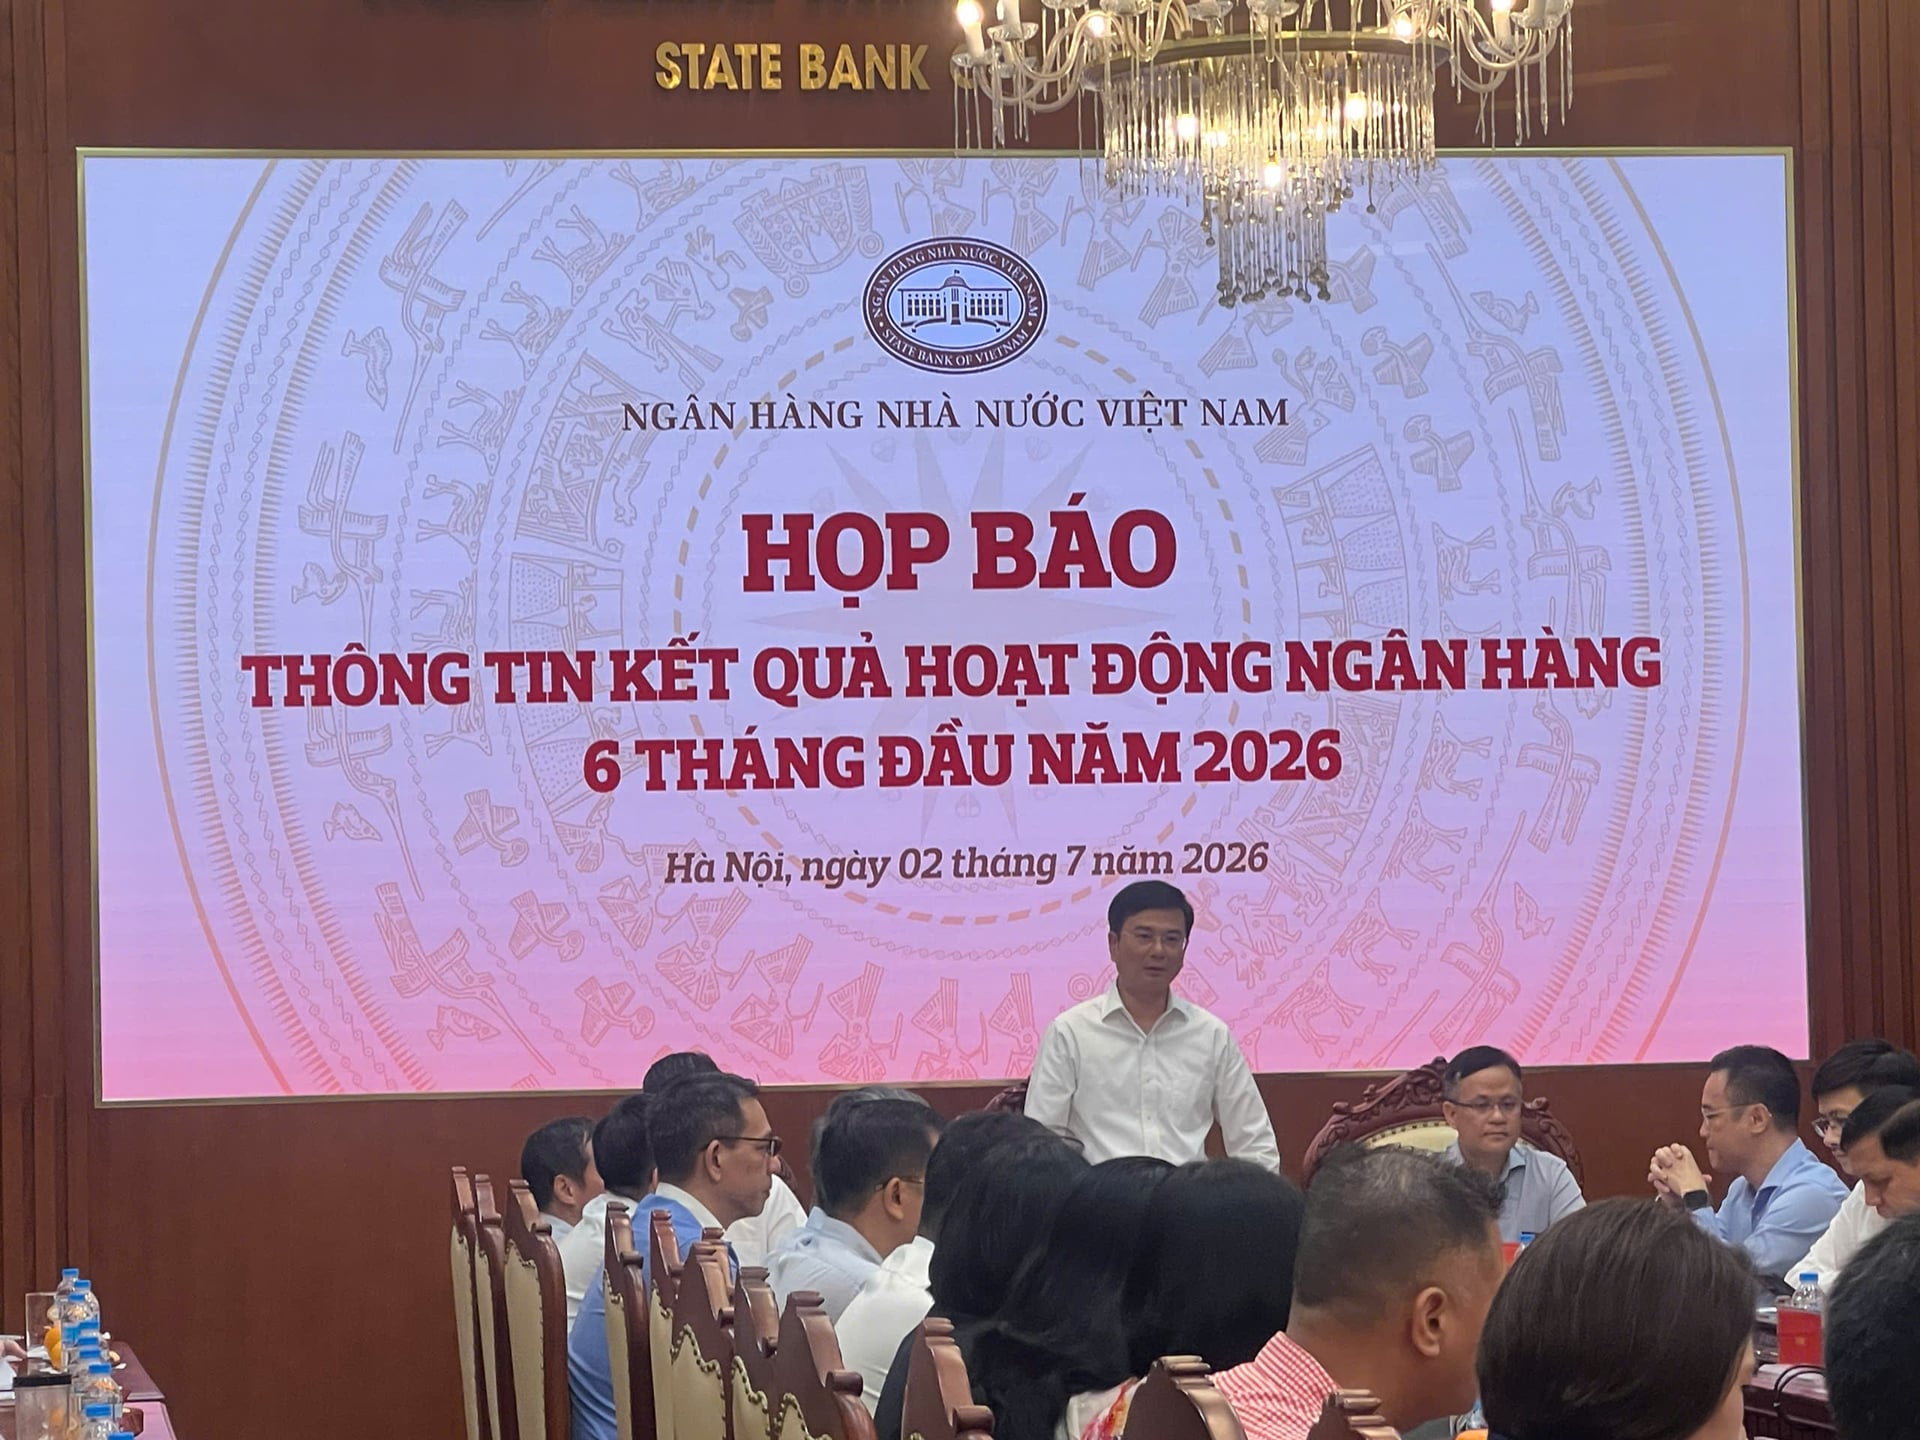
The State Bank of Vietnam affirms it will not reverse monetary policy. Photo: DP
On the other side, according to information shared by SBV leadership, deposit mobilization across the system has grown only about 1.3%. The considerable gap between the pace of credit and deposit growth has created pressure to balance funding sources at many banks.
On the details of this development, SBV Deputy Governor Pham Thanh Ha, together with a representative of the Credit Department for Economic Sectors, said deposit rates began edging up from April, while credit demand grew faster than the pace of deposits flowing into the system.
Against this backdrop, many banks had to raise deposit rates to attract more funds, both to meet rising lending demand and to ensure liquidity-safety ratios as required by regulations.
In reality, deposits remain the main source of input funds for credit institutions. Therefore, when credit grows faster than deposits, banks have to make deposits more attractive to supplement funding and ensure liquidity.
Notably, this pressure arose while the SBV’s policy direction remained unchanged. Therefore, the edging up of deposit rates at some banks does not reflect a tightening of monetary policy or widespread liquidity strain, but is mainly a consequence of the economy’s capital demand recovering faster than the pace of deposit mobilization.
Holding firm on monetary-policy direction
Looking only at the movement of deposit rates at some banks, quite a few might think the system’s liquidity is under pressure or that the SBV has begun shifting toward a monetary-tightening stance.
However, SBV Deputy Governor Pham Thanh Ha stressed that global economic fluctuations — from geopolitical tensions and inflationary pressure to the policy-adjustment trend of major central banks — do not change the SBV’s operating direction.
Accordingly, monetary policy continues to be operated in a proactive, flexible manner, in close coordination with fiscal policy, in order to control inflation, stabilize the macroeconomy and support growth.
This direction has also been clearly reflected in policy decisions throughout the first half of 2026. The SBV has kept policy interest rates unchanged, enabling credit institutions to access funds from the central bank at reasonable cost.
At the same time, the regulator has repeatedly asked banks to cut operating costs, accelerate digital transformation, improve governance efficiency and share part of their profits to create room to reduce lending rates.
After working sessions between SBV leadership and the banking system in recent months, many credit institutions have also proactively lowered deposit rates on new deposits at certain terms, while continuing to roll out credit packages with preferential interest rates for businesses and individuals.
This shows that the regulator’s overarching goal remains to keep lending rates at a reasonable level to support economic recovery and growth.
At the system level, rapid credit growth is a positive signal as funds are unlocked and flow more strongly into the economy. However, credit expanding faster than deposit mobilization also creates a requirement to rebalance input funds to ensure liquidity and comply with each bank’s safety ratios.
Therefore, the recent adjustment of deposit rates by some credit institutions reflects each unit’s need to supplement funds more than a change in overall policy direction.
To limit this pressure from spreading to lending rates, the SBV said it will continue to flexibly use liquidity-management tools, especially open market operations (OMO), to supply short-term funds to the system when necessary.
According to SBV leadership, right after the Governor’s operating meetings in May and June, market interest rates gradually stabilized again.
Along with supporting liquidity through the open market, the SBV continues to closely monitor supply-demand developments in order to regulate in a timely manner, thereby limiting the risk of funding costs rising too fast and spreading to lending rates.
More room to balance funding sources
In addition to regulating liquidity through short-term tools such as open market operations, the SBV is also gradually improving its policy framework to reduce deposit-mobilization pressure for the banking system in the medium and long term.
New policies help support liquidity for the banking system. Photo: HA
One notable change is the SBV’s issuance of Circular 08, which allows credit institutions to count 80% of the balance of term deposits from the State Treasury as mobilized funds when calculating the loan-to-deposit ratio (LDR), instead of fully excluding them as before.
An SBV representative on monetary policy said this adjustment helps banks make better use of deposits from the State Treasury in calculating safety ratios, thereby reducing the pressure to increase mobilization from residents and businesses merely to meet funding requirements.
At the same time, the state budget’s idle funds are used more effectively, helping support liquidity for the banking system and creating additional room to supply credit to the economy, especially key national projects.
These moves show the SBV’s efforts to balance three goals that are not easily reconciled: ensuring liquidity for the system, expanding credit to support growth, and keeping lending rates at a reasonable level.
Viewed more broadly, the movement of deposit rates in recent months reflects a change in the state of the banking system. Whereas in previous years the big challenge was stimulating loan demand when credit grew slowly, by mid-2026 the challenge has shifted to balancing funding sources to meet credit demand that is recovering faster than the pace of mobilization.
This change reflects a positive signal for the economy as capital demand for production, business and investment is clearly improving. However, it also places higher demands on monetary-policy management.
In a context where the Government sets a high economic-growth target, the banking system must both ensure sufficient capital supply for the economy and control funding costs so as not to increase the financial burden on businesses.
Source: TheLeader — theleader.vn. This article is republished to share knowledge with the community of founders and investors in the HCM VIF ecosystem.
Category & tags
Related news
 Ecosystem
Venture capital will be a new asset class
Mr. Hoang Duc Trung believes that, with the State taking the lead and large organizations and enterprises joining forces to spread the momentum, venture capital will fulfil its role as an engine of growth and innovation
 Finance & Banking05/2026
The success of a public-private venture fund is not measured by the number of unicorns
With an initial size of VND 500 billion, how will the government's “seed capital” from the public-private venture fund catalyze the flow of financing into startups?
 Finance & Banking18/05/2026
Ho Chi Minh City sets up venture capital fund: 'Seed capital' for Vietnamese tech
For the first time, Ho Chi Minh City has a venture capital fund operating under a joint-stock company model with the participation of the State and major private corporations.