

Big Investors Shift Appetite in Vietnam's M&A Deals
For many companies, M&A is no longer about growing bigger at any cost. It has become a tool for restructuring and for tightening control over the value chain.
For many companies, M&A strategy is no longer a game of expanding scale at any cost. It has become a tool for restructuring and for consolidating control within the value chain.
M&A enters a quality-first phase
Vietnam's M&A market is going through a “restructuring” after global economic turbulence. Deal counts are down from the post-Covid years, but deal quality and value have risen markedly, concentrated in strategic transactions that reshape an industry or a company.
The shift comes as the global economy absorbs the aftershocks of prolonged monetary tightening, persistent inflation in several key regions and the fragmentation of global supply chains caused by geopolitical tension. Companies have been forced to reassess their position in the value chain: which assets are core and must be kept, which should be divested, and which links must be acquired quickly to build long-term competitive advantage.
In Vietnam, a steady macroeconomic recovery, with second-quarter 2026 GDP growth of 8.39% and resilient FDI flows, has created a favourable base for investment, expansion and corporate restructuring.
Total registered foreign investment into Vietnam in the first six months of 2026 reached 34.65 billion USD, up 61% year on year, while disbursed FDI reached 13.03 billion USD, up 11.2%. Capital contributions and share purchases by foreign investors alone reached more than 6.2 billion USD, up 89.5%, showing that M&A remains an important channel for foreign capital to go deeper into the Vietnamese market.
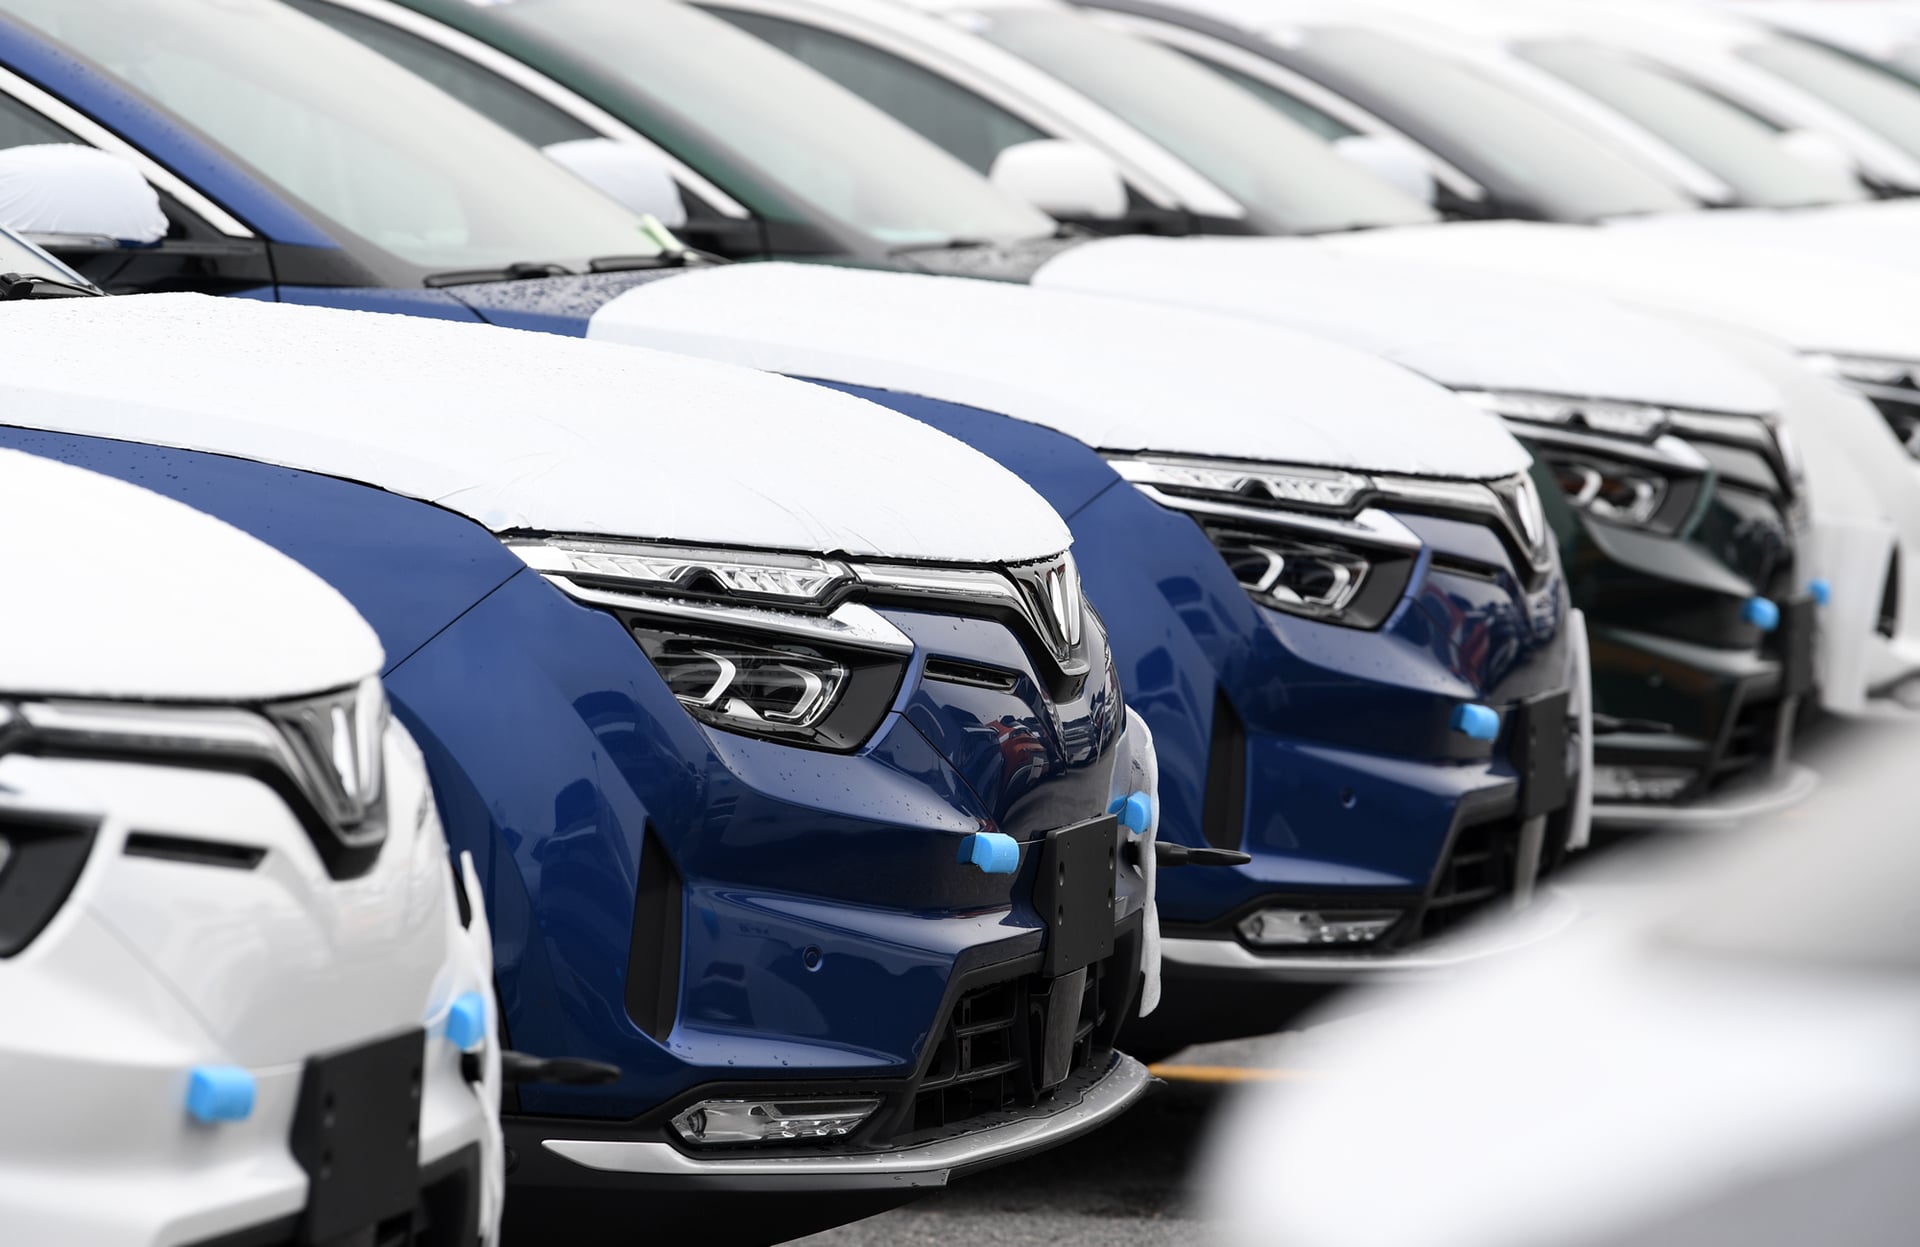
Among the most notable deals of the first half was VinFast's transfer of its entire stake in VinFast Trading and Production Joint Stock Company (VFTP) to the Future Investment group, which took 95.5% control, at a valuation of about 530 million USD (13.3 trillion dong).
What stands out is that this was not a peripheral M&A deal aimed at expanding into a new field, but rather a deliberate internal restructuring step.
By separating its manufacturing operations in Vietnam from its core international businesses, VinFast can reduce fixed-asset pressure, restructure its balance sheet and concentrate resources on higher value-added links such as research and development, branding, sales, after-sales service and global market expansion.
Seen from a market perspective, the deal reflects a new approach to M&A strategy: growing bigger does not necessarily require buying more; selling down, spinning off or restructuring ownership can make the business model leaner.
For a company in the middle of international expansion such as VinFast, shedding capital-heavy assets can improve capital efficiency, create financial headroom for more strategic activities and move it closer to improving profitability in the coming years.
A similar logic applies to Imexpharm, where Livzon Pharmaceutical Group filed to acquire nearly 78% of the company in a transaction expected to be worth close to 7 trillion dong. After the deal, Livzon, through Lian SGP Holdings, becomes Imexpharm's largest shareholder. The higher stake gives Livzon significant control over Imexpharm.
The rationale for acquiring Imexpharm lies in Livzon's need to expand its presence in a pharmaceutical market with substantial room to grow. Imexpharm's appeal lies not only in its size but in its position in the high-quality drug segment. It operates plants certified to EU-GMP and WHO-GMP standards, including three EU-GMP clusters and one WHO-GMP cluster.
That is a major advantage in pharmaceuticals, where technical barriers, manufacturing standards, drug registration systems and hospital distribution channels directly determine the ability to expand market share.
In healthcare, the pharmacy chain Pharmacity is another notable case, raising growth capital from LeapFrog Investments, an impact fund focused on healthcare, financial services and other essential sectors in emerging markets.
Although the deal value was not officially disclosed, the transaction shows growing international interest in Vietnam's pharmaceutical retail market, particularly as demand for healthcare, quality medicines and convenient medical services rises rapidly. According to LeapFrog, Pharmacity now has more than 1,100 pharmacies nationwide, serving nearly 19 million loyalty customers, and is targeting 500 additional stores over the next three years.
Analysts note that while the Imexpharm deal reflects a strategy of buying control in pharmaceutical manufacturing, Pharmacity points in a different direction: investing in a retail platform that has completed its restructuring phase and begun to demonstrate operating efficiency.
Pharmacity has been profitable for several consecutive quarters since the fourth quarter of 2025, with revenue growth of more than 35% in the first quarter of 2026 and same-store sales growth above 20% in the same period. These figures show investors are looking beyond network size to profitability, per-store efficiency and the prospects for sustainable expansion.
In financial services, Kredivo Group announced it had completed the acquisition of nearly 100% of Timo Digital Bank, a strategic step to expand its presence in Vietnam and strengthen its position in digital financial services in Southeast Asia. The deal followed a fundraising round from new and existing investors including Mizuho Bank, Amazon, Asia Partners, Square Peg Capital and Cathay Innovation.
Founded in 2015, Timo is one of Vietnam's pioneering digital banking platforms, built in partnership with BVBank. It offers a broad retail banking ecosystem including online account opening, payments, savings and term deposits, serving a growing digital customer base.
According to Akshay Garg, co-founder and CEO of Kredivo Group, acquiring a majority of Timo means the platform does not have to "start from zero" but takes over a brand that has already earned the trust of Vietnamese users.
In real estate, the shift towards strategic M&A is clearly illustrated by Phat Dat. After years of being known mainly as a big player that "buys and flips", Phat Dat has gone all in on a capital contribution to Lotte Eco Smart City Thu Thiem, betting on an opportunity that could upgrade its long-term standing.
To secure resources for a project requiring investment in the tens of trillions of dong, Phat Dat agreed to sell several prized assets including Thuan An 1, Thuan An 2 and Serenity Phuoc Hai. According to management, Lotte Eco Smart City Thu Thiem is a chance for Phat Dat to establish a "new position" in the market, not only in terms of project scale but in how the company redefines its role in the property development chain.
Companies need to seize the opportunity early
Overall, the vibrancy of the M&A market in the first half of this year is evident not only in deal size or volume but in a clear change in how investors allocate capital. The deals above are only a sample, but they show capital moving towards companies, projects and business platforms that are relatively complete, ready to execute, capable of generating stable cash flow and able to demonstrate operating efficiency, rather than assets that rely largely on hopes of future price appreciation.
According to Ta My Bach, Head of Capital Markets at JLL Vietnam, the market has shifted markedly from investment strategies based on expected price gains to strategies based on asset quality and actual operating performance. With the cost of capital still high, investors increasingly favour projects that can generate stable cash flow, hold long-term competitive advantages and meet sustainable development standards. These will be the decisive factors in the market's ability to attract capital in the next phase.
Nguyen Thanh Ha, Chairman of SBLaw, agrees, saying the market no longer assesses companies by revenue or profit alone. Greater attention now goes to governance capability, transparency, operating efficiency and the ability to grow sustainably. These are precisely the requirements of the high-quality M&A phase Vietnam is moving towards.
Importantly, Vietnam's expected upgrade by FTSE to emerging market status in September 2026 could act as a significant catalyst for the next M&A cycle. The upgrade would improve liquidity, stabilise IPO valuations and create more effective exit routes for investment funds.
That also means companies will face heavy pressure to change, investing more in technology to improve their business models and adopt modern governance standards if they hope to attract investor attention quickly.
From another angle, the biggest barrier in the market today is neither liquidity nor investor interest, but the price expectation gap between buyers and sellers. While many owners expect valuations that reflect the market's recovery prospects, international funds remain cautious after a volatile period for the global economy.
That gap is expected to narrow gradually as market confidence improves and more successful deals are recorded.
Source: TheLeader — theleader.vn. Republished to share knowledge with founders and investors in the HCM VIF ecosystem.
Category & tags
Related news
 Ecosystem
Venture capital will be a new asset class
Mr. Hoang Duc Trung believes that, with the State taking the lead and large organizations and enterprises joining forces to spread the momentum, venture capital will fulfil its role as an engine of growth and innovation
 Finance & Banking05/2026
The success of a public-private venture fund is not measured by the number of unicorns
With an initial size of VND 500 billion, how will the government's “seed capital” from the public-private venture fund catalyze the flow of financing into startups?
 Finance & Banking18/05/2026
Ho Chi Minh City sets up venture capital fund: 'Seed capital' for Vietnamese tech
For the first time, Ho Chi Minh City has a venture capital fund operating under a joint-stock company model with the participation of the State and major private corporations.