

Many banks exposed for shortcomings in credit activities
The State Bank Inspectorate pointed out signs of risk in lending and debt-handling activities at many banks such as Agribank, BIDV and VietinBank.
The State Bank Inspectorate pointed out signs of risk in lending and debt-handling activities at many banks such as Agribank, BIDV and VietinBank.
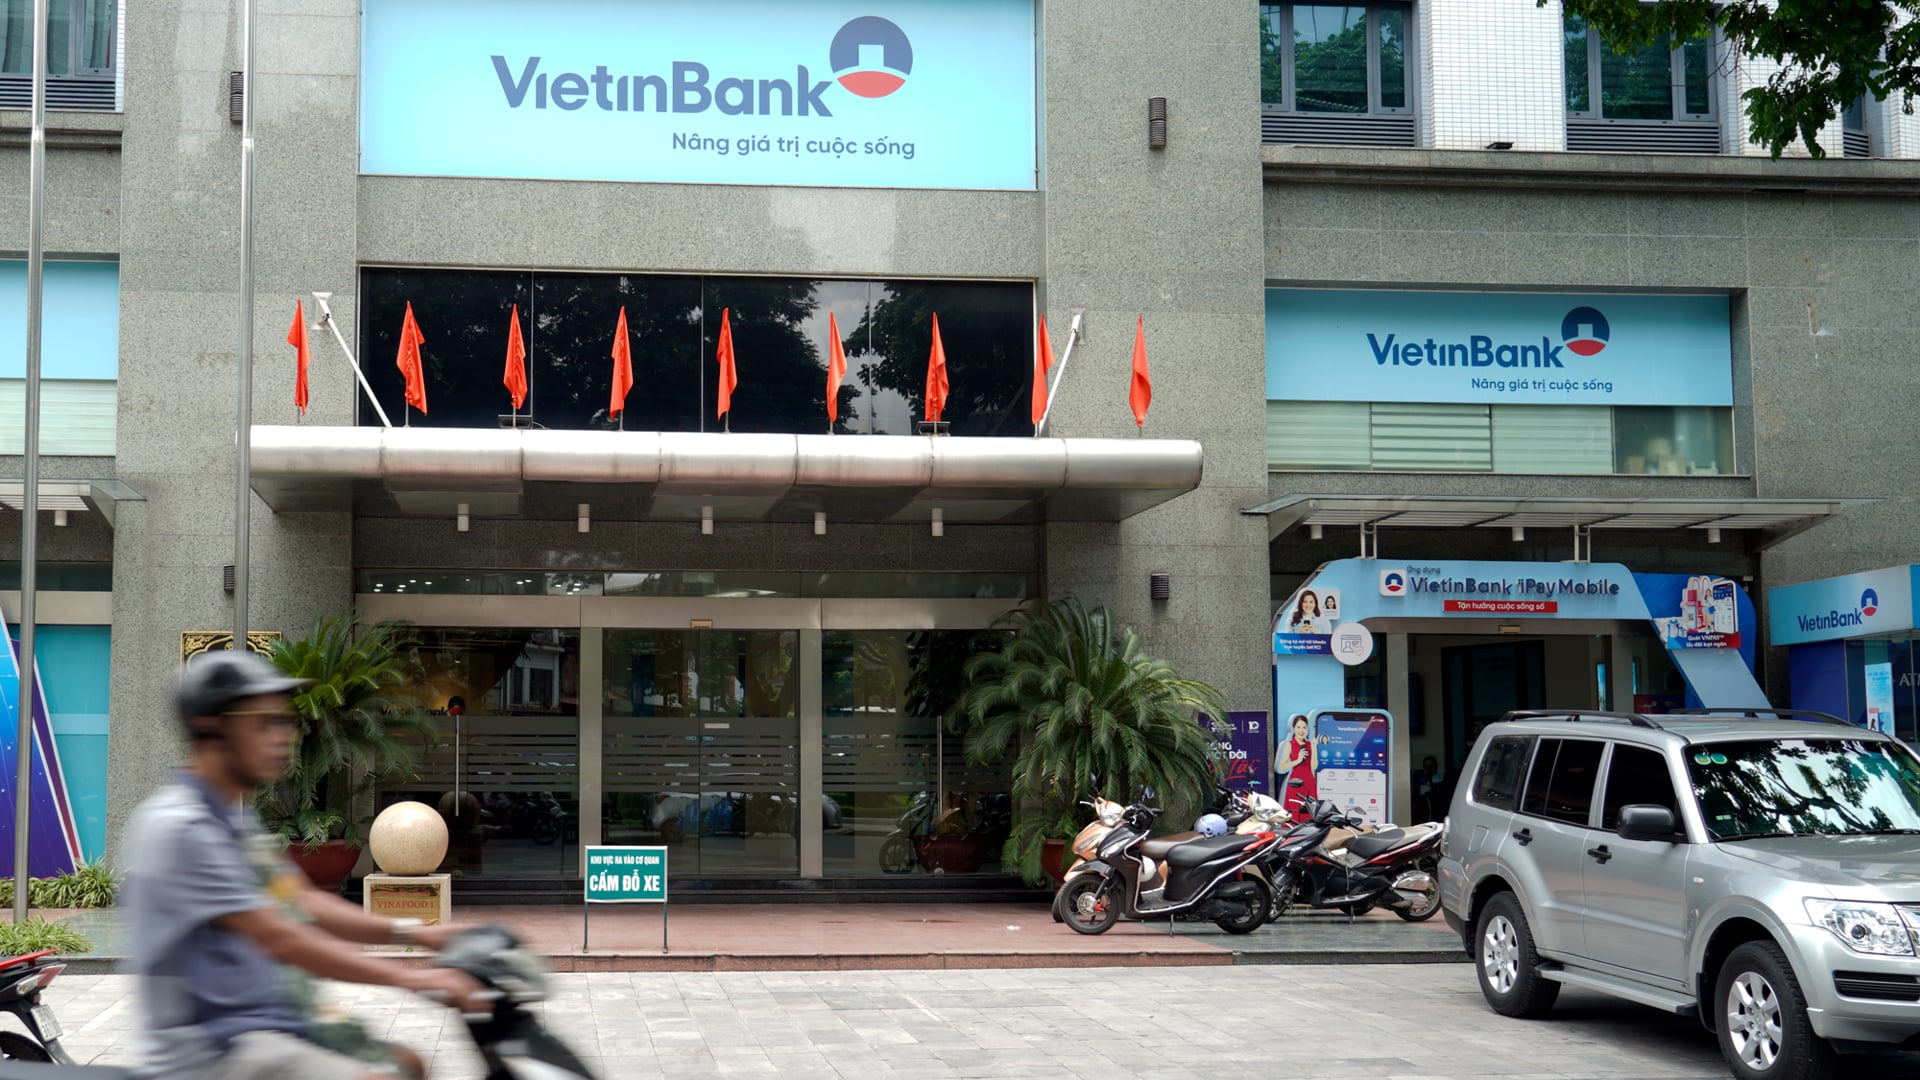
Many shortcomings in VietinBank's operations have been clearly pointed out by the inspection agency. Photo: Hoang Anh
According to the conclusion of the State Bank Inspectorate, Agribank's Nghi Loc Nghe An branch and Ha Tinh branch still had some shortcomings in appraising, approving loans and inspecting the use of loan capital.
At Agribank Dak Lak, the unit with the largest loan balance (accounting for 11.7%) among the total of 49 credit-institution branches operating in the West Dak Lak area (former Dak Lak province), there were still some limitations and errors related to collecting information, documents and data proving customers' financial capacity, appraising feasible capital-use plans, and the lawful purpose of capital use.
At the same time, although Agribank Dak Lak had hired a valuation-function unit to survey, appraise and specifically determine a land-price table applied uniformly across the area, some lending units still accepted valuation certificates provided by customers at higher values to determine collateral as the basis for the loan amount, which entails potential risk.
The authorities determined that the inspection and supervision of customers using loan capital for the proper purpose at Agribank Dak Lak was not sufficiently rigorous and did not collect full information related to customers' capital-borrowing needs. In addition, the work of appraisal, inspection and post-lending supervision still recorded some shortcomings.
Regarding Agribank's Kien Giang II branch, the State Bank Inspectorate for Region 15 concluded that there were still limitations in appraising, inspecting and supervising loan capital, as well as in handling and recovering bad debt. At the same time, the branch's operations also gave rise to some signs of potential risk that need attention.
According to Mr. Le Dinh Khanh, Chief Inspector of the State Bank for Region 15, the shortcomings and risk signs at Agribank Kien Giang II have not caused asset losses, but they need to be corrected and remedied promptly to ensure the unit's operational safety.
According to statistics from Agribank's Kien Giang II branch, in 2019 the branch's total loan balance reached over VND7,600 billion, of which the share of lending to the agricultural and rural sector accounted for over 98%.
At the end of April 2026, reports from the directors of Agribank's branches in the southern and southwestern regions showed that debt-handling work still faced many difficulties, especially in the context where some agricultural production sectors are undergoing many shifts in crop orientation, as well as impacts caused by climate change.
As for Agribank's North Thanh Hoa branch, it continued to be a unit recording a series of shortcomings, limitations and findings and assessments that could affect credit-extension activities, including appraisal and approval of credit extension; post-lending inspection and supervision; credit dossiers and collateral.
At BIDV's Dong Nai branch, the Deputy Chief Inspector of the State Bank for Region 2 concluded that there remained violations and limitations needing correction and remedy related to appraising and approving loans, handling bad debt and implementing bad-debt-handling solutions. Similar errors related to loan appraisal and approval and/or the handling of problem debts were also pointed out at Vietcombank's Binh Thuan branch and BaovietBank Dak Lak.
In addition, the inspection agency also concluded that there were errors and potential risks in credit-extension activities, bad-debt handling and off-balance-sheet bad-debt recovery at PGBank's Khanh Hoa branch.
Beyond the credit risks arising at branches, the State Bank Inspectorate also pointed out issues related to the management and use of assets and investment capital at VietinBank.
Specifically, at VietinBank there are four housing and land facilities left vacant for many years but not yet built into working offices. This bank has also been slow to implement some approved projects.
At the same time, the implementation of some projects behind schedule, dragging on for many years compared with the original plan and requiring the schedule to be adjusted multiple times, has generated project-management costs, indirect costs and opportunity costs, failing to ensure the efficient use of investment capital in line with the project's original objectives.
According to the inspection agency, some of VietinBank's housing and land facilities have most of their usable area leased out; some organizations and businesses using the leased space do so for improper purposes; and some housing and land facilities are being managed and used but do not yet fully ensure legal standing. VietinBank is currently managing and using a total of 745 housing and land facilities.
Regarding credit activities, the State Bank Inspectorate also pointed out shortcomings at VietinBank's Hung Yen branch in the appraisal, inspection and supervision of loan capital. Meanwhile, VietinBank's Hue branch recorded some loans showing signs of potential risk, related to the financial situation and collateral of customers.
Source: TheLeader — theleader.vn. This article is republished for the purpose of sharing knowledge with the community of founders and investors within the HCM VIF ecosystem.
Category & tags
Related news
 Ecosystem
Venture capital will be a new asset class
Mr. Hoang Duc Trung believes that, with the State taking the lead and large organizations and enterprises joining forces to spread the momentum, venture capital will fulfil its role as an engine of growth and innovation
 Finance & Banking05/2026
The success of a public-private venture fund is not measured by the number of unicorns
With an initial size of VND 500 billion, how will the government's “seed capital” from the public-private venture fund catalyze the flow of financing into startups?
 Finance & Banking18/05/2026
Ho Chi Minh City sets up venture capital fund: 'Seed capital' for Vietnamese tech
For the first time, Ho Chi Minh City has a venture capital fund operating under a joint-stock company model with the participation of the State and major private corporations.